Accounting firms send confirmation letters to third parties to assess the accuracy of an auditee's financial statements.
Under Article 20 of the Company Act, Article 102 of the Income Tax Act, and Article 3 of Standards on Auditing No. 8, companies whose equity capital reaches a prescribed amount, or falls below that amount but reaches a certain scale, shall have their financial statements and annual profit-seeking enterprise income tax returns audited and certified by a CPA. When certifying financial statements or income tax returns, auditors may send confirmation letters to third parties as an audit procedure to obtain and evaluate audit evidence.
Upon receiving confirmation letters, TDCC devotes considerable staff time and resources to their verification and response.
Each January and July, TDCC carries out CPA audit confirmation operations. These operations were previously paper-based, with documents sent by post. TDCC accepted audit confirmation letters for its participants (including securities firms, bill dealers, cross-border custodian participants, and clients of custodian institutions, but excluding issuers with dematerialized book-entry registration).
The accounting firm first mailed the confirmation letter to the participant, requesting the participant to affix the specimen seal registered with TDCC; the participant mailed the sealed confirmation letter back to the accounting firm, and the accounting firm then mailed the sealed confirmation letter to TDCC. After confirming that the seal on the confirmation letter matched the participant's specimen seal on file with TDCC, TDCC generated the relevant inquiry statements based on the account numbers specified in the confirmation letter, and then mailed a copy of the confirmation letter and the inquiry statements to the accounting firm.
The above procedure often gave rise to situations such as incorrect participant seals, missing account numbers, and non-TDCC participants. The documents had to be returned by mail to the accounting firm, and then the accounting firm made corrections and mailed the confirmation letter again to proceed with the audit confirmation.
The "Online CPA Audit Confirmation Application" electronic service was launched on July 1, 2026.
To implement the corporate development strategy of promoting sustainable transformation through ESG and to optimize the efficiency of CPA audit confirmation operations, TDCC launched the "Online CPA Audit Confirmation Application" electronic service on July 1, 2026. The service aims to reduce internal manual processing costs, effectively save paper and postage, as well as accelerate accounting firms’ audit efficiency.
Electronic CPA Audit Confirmation Process:
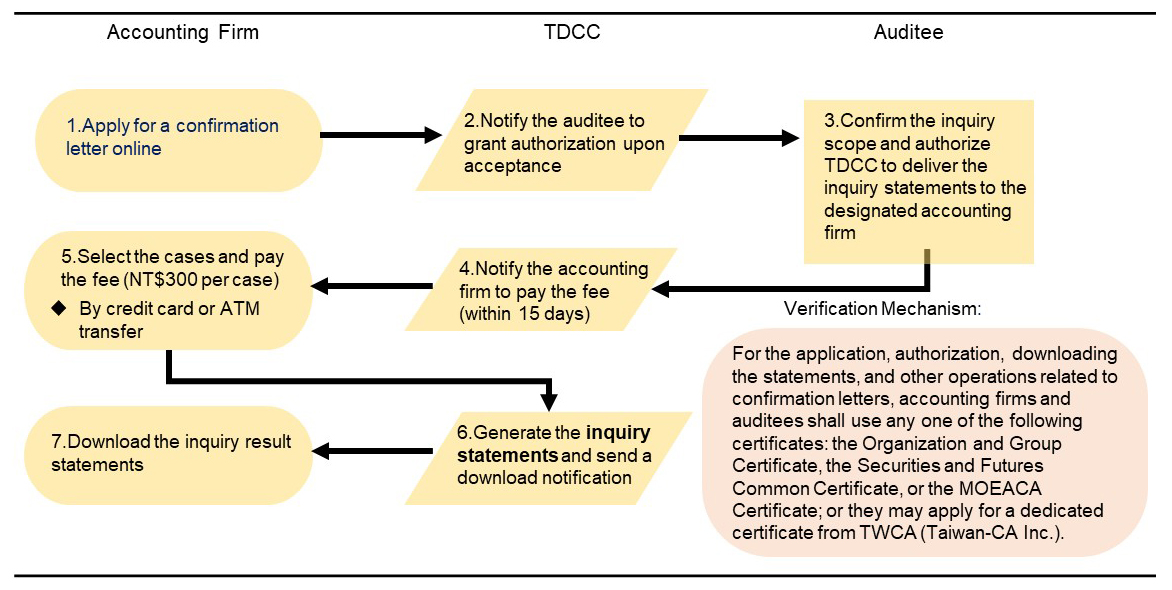
Key adjustments to the related operations are as follows:
I. Electronic certificates replace participants' registered specimen seals.
To verify the identities of the accounting firm and the auditee, both parties should log in to TDCC's website to apply for the retrieval of CPA audit confirmation data online. Operations including the application for confirmation letters, the confirmation and authorization of the inquiry scope, payment of inquiry fees, and downloading of inquiry result statements must be verified with an electronic certificate (any one of the Organization and Group Certificate, the Securities and Futures Common Certificate, or the MOEACA Certificate, or a dedicated certificate obtained from TWCA).
II. Electronic audit confirmation is not limited to TDCC participants, and consolidated inquiries are permitted.
To broaden the use of electronic CPA audit confirmation, profit-seeking enterprises or other groups or institutions with legal personality may also apply through TDCC's website. Accounting firms may conduct consolidated inquiries by the company's Unified Business Number; with a single application, they can access the auditee's balance data at all securities firms. In addition to the share balances in book-entry custody accounts at securities firms, balances in various special accounts may also be inquired into, such as pledges securities, margin securities, and collateral for lending arrangements.
III. Greater flexibility in inquiry reference dates.
The reference date for balance inquiries in confirmation letters was originally set by default to June 30 and December 31 of each year. However, since accounting firms also need audit confirmations for auditees' initial public offerings (IPOs), reinvestment shareholdings, and mergers and acquisitions, the inquiry reference date is not limited to specific dates.
IV. Adopting a User-Pays Principle to Improve Resource Allocation Efficiency
When an accounting firm applies for a confirmation letter to inquire about an auditee's data, a fee of NT$300 is charged per confirmation letter (for both electronic and paper-based audit confirmations). Except for auditees that are TDCC participants may use paper-based audit confirmation (including securities firms, bills finance companies, cross-border custodian participants, and clients of custodian institutions, but excluding issuers with dematerialized book-entry registration) , TDCC ceases accepting paper-based audit confirmations in conjunction with this electronic service.
In the future, TDCC will continue to enhance customer service based on market practices and operational experience to improve operational efficiency. In addition, in line with the company policy, TDCC will realize its vision of "enhancing the financial asset depository platform, leading digital innovation in financial services, and jointly promoting the sustainable development of financial markets."
